


The Uganda shilling remained under pressure against the US dollar on Monday, with the Bank of Uganda quoting the dollar at Shs 4,429.76 for buying and Shs 4,439.76 for selling, amid renewed debate over measures to slow the currency’s depreciation.
The pressure comes as the central bank prepares to auction government Treasury bonds worth Shs 1.4 trillion on Wednesday, October 28, in an operation that will be closely watched alongside other monetary policy measures aimed at managing financial market conditions.
According to an auction notice issued by the Bank of Uganda, the government intends to raise Shs 250 billion through two-year bonds, Shs 350 billion through five-year bonds, Shs 450 billion through 15-year bonds and Shs 350 billion through 25-year bonds.
The securities carry coupon rates ranging from 15 to 16 per cent, and the auction involves the reopening of existing government bonds. Treasury bond sales can affect domestic liquidity and interest rates, although the central bank’s notice does not identify the auction as a direct intervention to support the shilling.
The currency’s continued weakness has intensified discussions about whether the Bank of Uganda should increase its interventions in the foreign exchange market, particularly by selling dollars from its reserves to ease demand and limit sharp movements in the exchange rate.
On October 14, the central bank raised its Central Bank Rate by 2.25 percentage points to 12 per cent in response to inflationary pressures, concerns about the shilling’s depreciation and rising global energy costs.
The Bank of Uganda subsequently returned to the foreign exchange market on October 22 to sell dollars, highlighting the challenges facing policymakers as they seek to contain currency pressures without undermining the country’s external reserves.
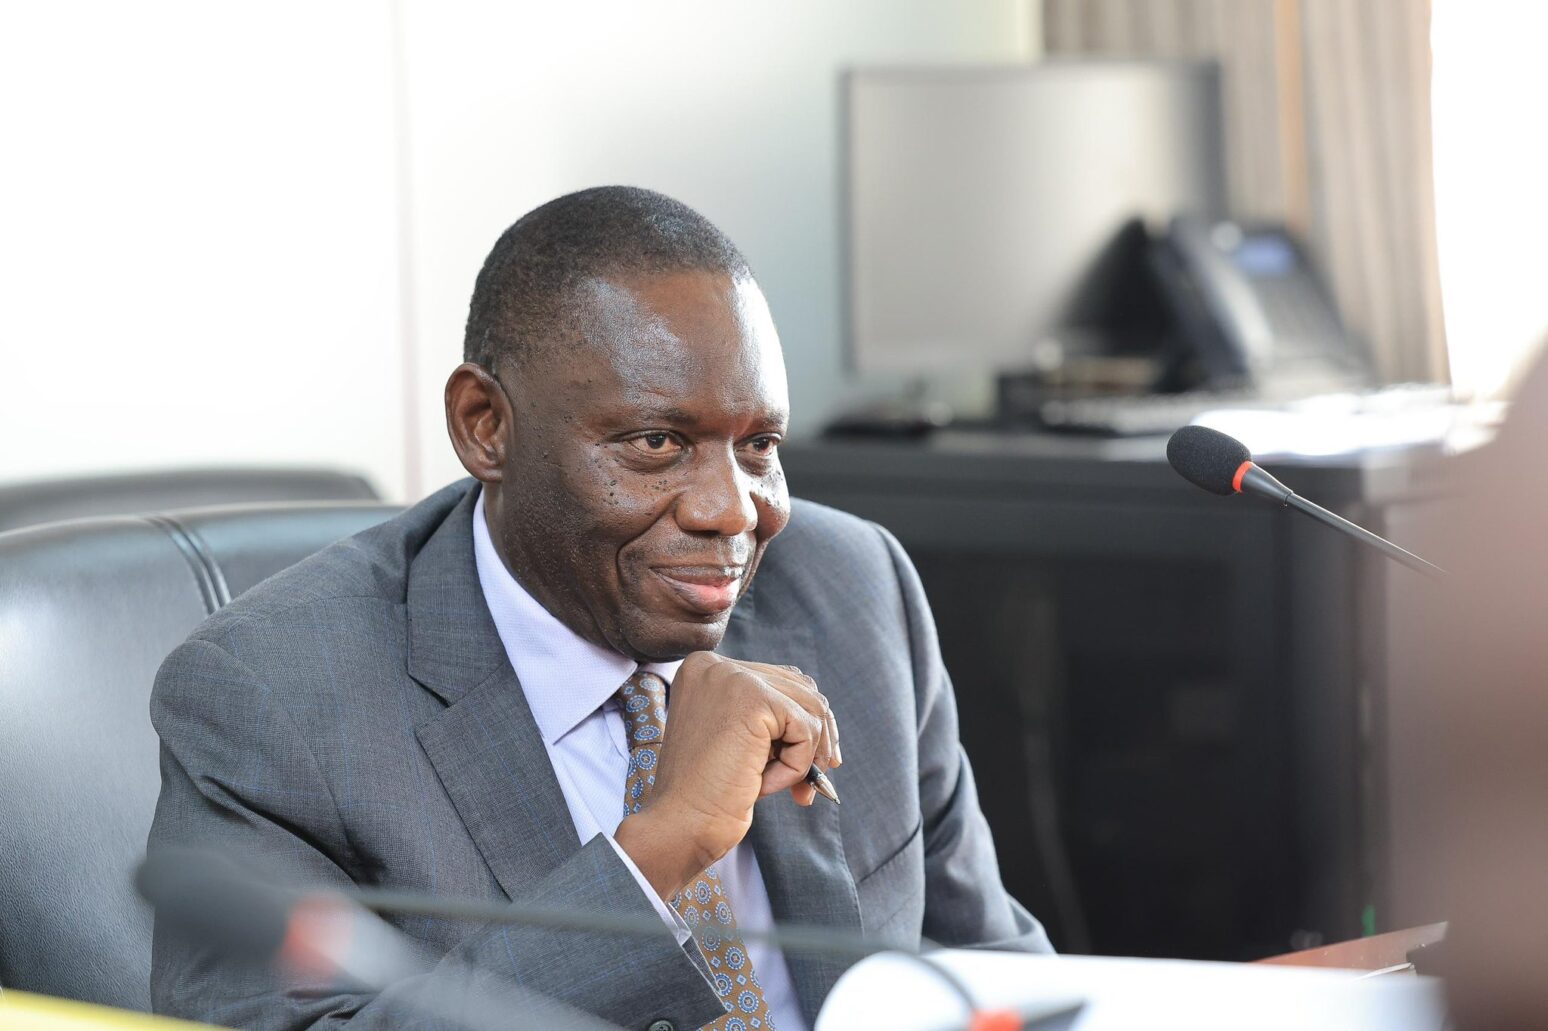
Against this background, Morrison Rwakakamba, the former chairman of the Uganda Investment Authority, has proposed a package of measures that he says could slow the shilling’s depreciation without depleting the central bank’s reserves or attempting to impose a fixed exchange rate.
In a paper dated October 23 and titled Breakdown of THIRD PATH Measures to Contain the Weakening of Uganda Shilling, Rwakakamba recommends targeted dollar sales, preferential foreign exchange access for essential imports and temporary measures to discourage the accumulation of dollars.
He proposes that the central bank limit its dollar sales to US$150 million in October, followed by US$250 million in November and another US$250 million in December. The proposed interventions, he argues, would help calm market anxiety and reduce panic-driven demand for foreign currency.
Rwakakamba also recommends that the Bank of Uganda publish weekly figures detailing its dollar sales to enable the public to assess the scale of intervention and monitor the potential impact on the country’s foreign exchange reserves.
His argument is that expectations of further depreciation can encourage businesses and individuals to buy and hold dollars as a safeguard against future losses. Such behaviour can increase demand for foreign currency, adding to the pressure on the shilling and potentially reinforcing expectations of further depreciation.
To address the cost of essential imports, Rwakakamba proposes a temporary foreign exchange facility that would provide dollars at a slightly more favourable rate to importers of fuel, fertiliser, essential medicines and wheat.
Under the proposal, the facility would support the importation of critical commodities, with the dollars expected to circulate back into the market when the imported goods are sold. This, he argues, would allow foreign exchange reserves to support essential economic activity without creating a permanent subsidy.
Importers dealing in non-essential goods would continue to access foreign currency at prevailing market rates.
Rwakakamba further suggests introducing a temporary measure that would make holding dollars marginally more expensive, with the aim of discouraging speculative accumulation and encouraging foreign currency to return to circulation. However, the paper would require further clarification on how such a measure would work in practice, including its legal and operational implications.
The proposals present an alternative approach to relying primarily on interest rate increases or leaving the exchange rate to respond to prevailing demand and supply conditions. Their effectiveness would depend on implementation, market response and the availability of sufficient foreign exchange to meet legitimate demand.
The shilling’s depreciation has significant implications for businesses that depend on imported fuel, machinery, medicines and industrial raw materials. As the currency weakens, importers require more shillings to settle the same dollar-denominated invoices, increasing operating costs.
Businesses may respond by raising prices, reducing profit margins or cutting back on investment and production. Higher import costs can also feed into transport charges, manufacturing expenses and the prices consumers pay for essential goods.
The challenge for policymakers is to ease pressure on the currency while preserving adequate foreign exchange reserves, containing inflation and maintaining confidence in the economy. Whether a combination of targeted interventions and tighter monetary policy can achieve that balance remains a key question as the shilling continues to face pressure.



 English
